Both walk the house. Only one is telling you whether to buy it.
An appraisal answers what it is worth. An inspection answers what is wrong with it.
People mix them up, often while deciding which one to skip. On most purchases you want both.
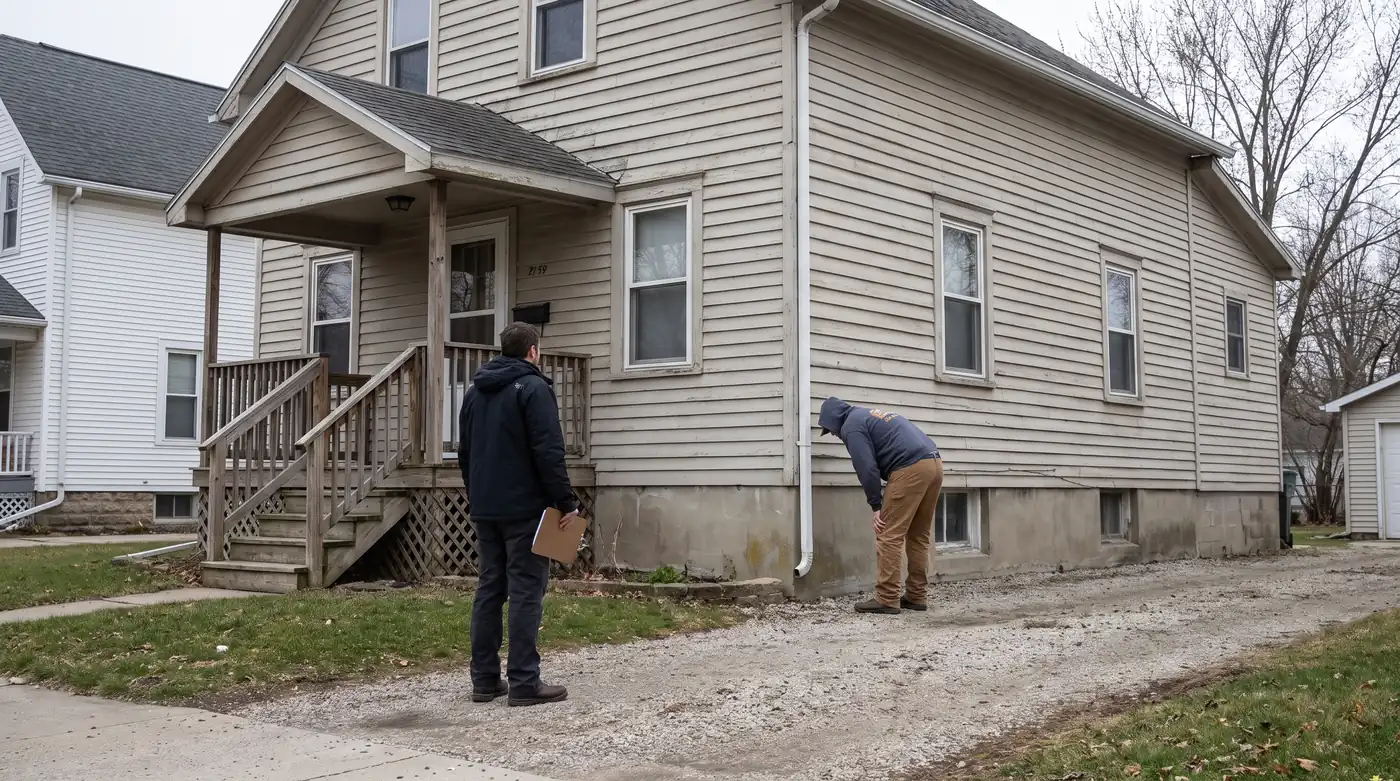
Two reports, two questions
The appraiser protects the lender's collateral. The inspector protects you. Those are not the same interest.
Appraisal
- Ordered by
- The lender, usually through an appraisal management company
- Paid by
- The borrower, on a loan
- Who performs it
- A state licensed or certified appraiser
- Main output
- An opinion of market value as of a specific date
- Condition
- Noted only where it affects value
- Required
- Yes, on most mortgages
- Who gets the report
- The lender, with a copy to the borrower
Home inspection
- Ordered by
- The buyer, directly
- Paid by
- The buyer
- Who performs it
- A home inspector, licensed in many but not all states
- Main output
- A list of defects, safety issues and remaining service life
- Condition
- The whole point of the visit
- Required
- No, it is a choice
- Who gets the report
- You
Why a buyer usually wants both
An appraisal at or above the contract price tells you the lender's collateral is sound. It tells you almost nothing about the furnace, the roof, the wiring or the drainage. The appraiser is not crawling the roof space or testing outlets. That is not the assignment.
So a fine appraisal is no reason to skip the inspection. The appraisal was never looking for those problems.
Where the two overlap
An appraiser does report condition where it affects value or lender requirements. Visible damage, an unsafe condition, a roof at the end of its life or missing handrails can all show up in an appraisal. On some loan programs they trigger a required repair and a reinspection.
The difference is depth and intent. The appraiser notes condition as it affects value. The inspector goes looking for problems on your behalf and has no view on what the house is worth.
Here is where it bites. A condition issue in the appraisal can hold up your loan. The same issue in the inspection gives you room to negotiate.
For the valuation half
The inspection is yours to book with whichever inspector you trust. The appraisal normally runs through your lender, but if you need a residential appraisal ordered for another reason, such as a private sale, you can arrange the appraisal side with Pocket Appraisal, a national residential appraisal service.
Common questions
Do I need both an appraisal and an inspection?
Will the appraiser find problems with the house?
Can the appraisal kill my deal?
Which one happens first?
Not sure which one you need?
Describe where you are in the process and what you are trying to find out.